
Wrestling With Medicare
I retired twelve years ago at age 67. Not by choice, mind you, but because my employer at the time, the College of Marin (Kentfield, CA), thought it was time for me to go. I was not entirely prepared for this particular transition. All of a sudden, I had to thoroughly examine where I was in life, assess my finances, and make some highly consequential decisions.
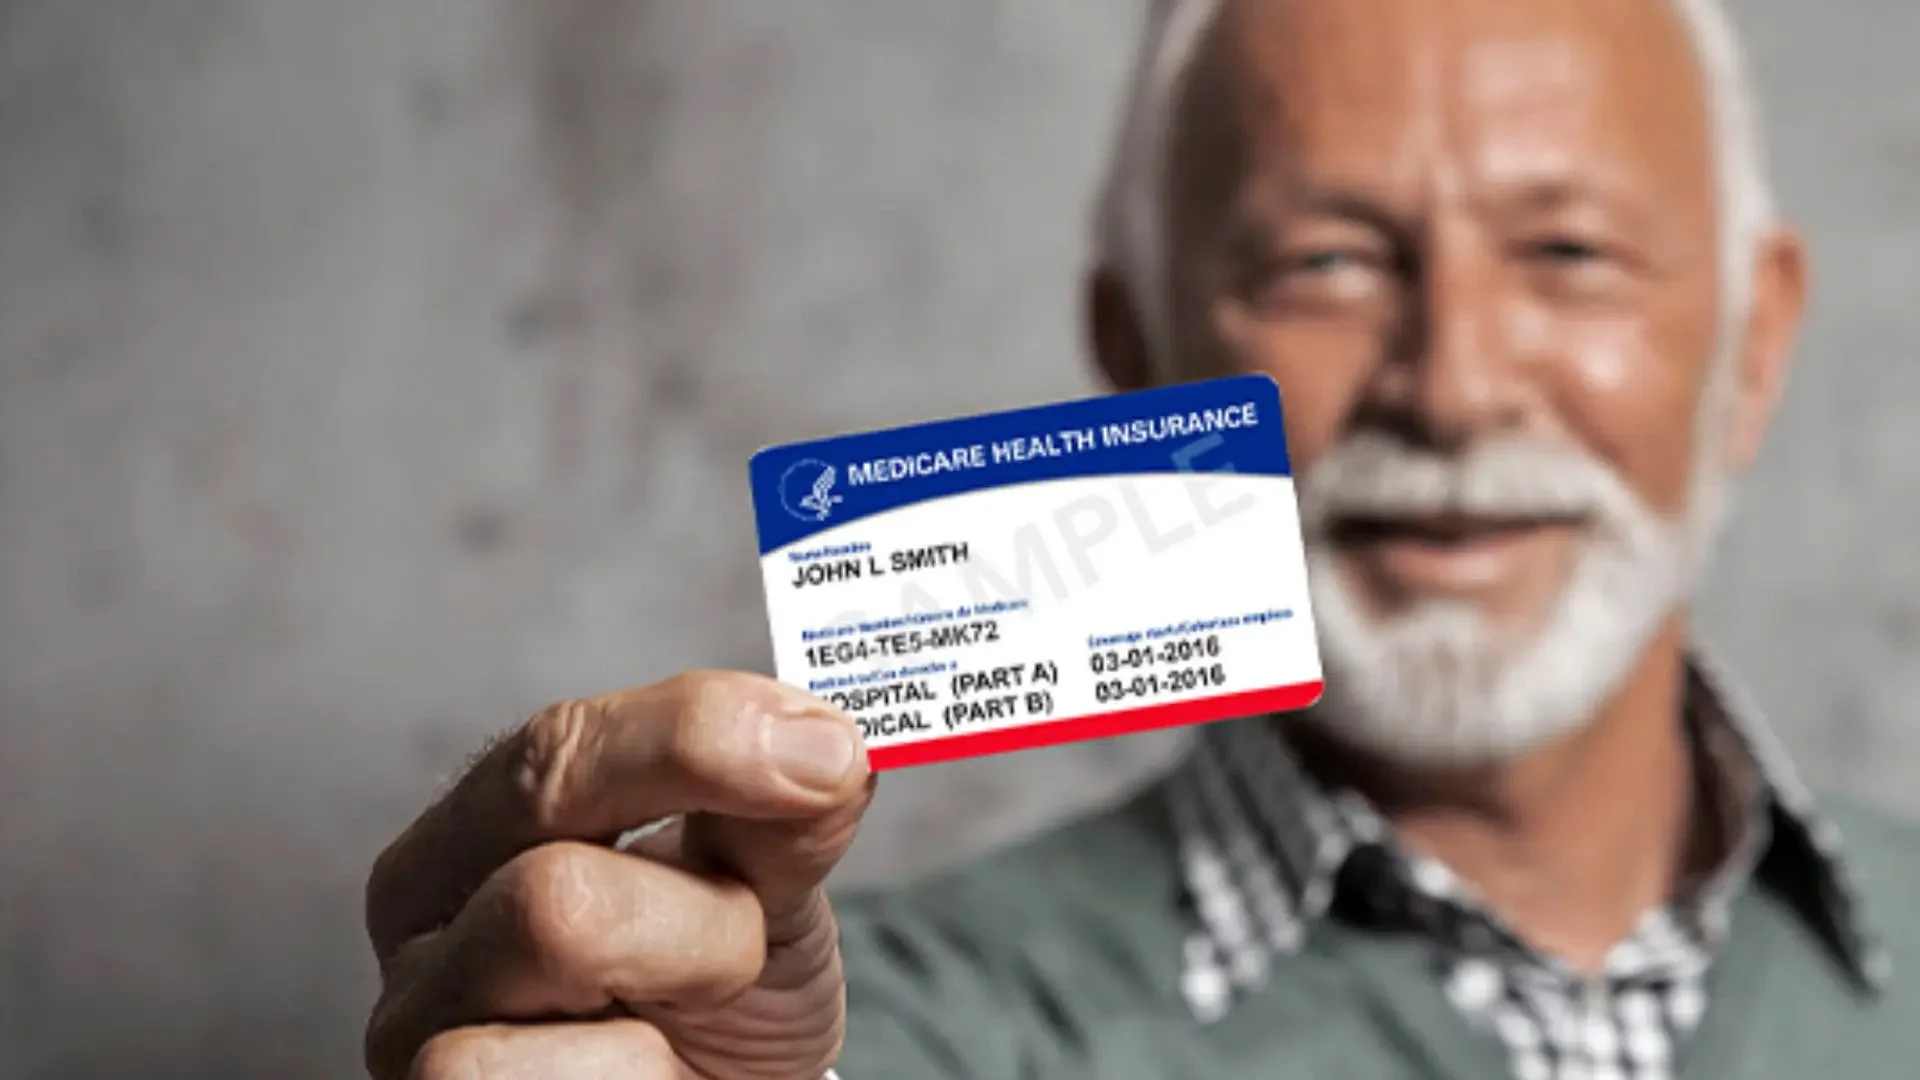
One of my tasks involved trying to familiarize myself with the Medicare system. I had enrolled at age 65, but I was not relying on it because I was still employed and had a great employer-supplied health plan. Then, there I was: unemployed. I had to get my ducks in a row.
So, okay, the challenge was to figure out Medicare for real. It was not easy. I discovered an astonishingly complicated bureaucracy filled with unfamiliar terminology, competing plans, enrollment periods, coverage rules, and financial consequences. “Fuck. I don’t have time for this” (I thought). Of course, I had to make the time.
To understand the basic choices, I bought the 2014 edition of Medicare For Dummies. For I was truly a dummy. I learned there was Original Medicare, as well as Medigap, prescription-drug coverage, and Medicare Advantage plans. I ultimately went with Medicare Advantage. (These days, 55 percent of eligible Medicare beneficiaries do the same.) The choice offered some welcome familiarity because its premiums, provider networks, copayments, and other mechanics tended to resemble my employer-provided insurance.
I have remained with the same insurer ever since I started. For the most part, I have been satisfied with both the coverage and customer service. But satisfaction does not eliminate the need for vigilance. Every year during open enrollment, I have compared plans, confirmed that my doctors remain in network, reviewed prescription-drug coverage, and calculated the likely overall costs.
This year has been more frustrating than usual. I found that some of the Medicare Advantage providers are different than previous years. My plan is changing its name and increasing its monthly premium. My prescription coverage is also becoming less generous. A couple of generic meds I routinely take are being moved into a more expensive tier, now subject to a $600 annual deductible, something I have never faced before.
In addition, two more issues have arisen. In the last week, my insurer denied coverage for an epidural steroid injection in my spine, a routine procedure I have received before. It also denied reimbursement for my chiropractic visits, even though I have submitted receipts and received reimbursement for approximately the last four years. Today, I spent a stressful hour on the telephone trying to resolve these issues. That hour represents only the latest installment of the time and energy required to obtain benefits I believed were already included.
I pay attention. I read the annual notices of changes. I know how to work through a bureaucracy, and I am not afraid to ask questions or challenge a decision. Even so, this process is fucking exhausting.
This leaves me deeply concerned for other seniors who may struggle to understand complicated documents, make difficult telephone calls, use online comparison tools, or navigate an appeals process. Television commercials constantly remind us to “check our coverage,” as though it were a simple task. In reality, it takes time, confidence, persistence, and often outside help.
I don’t believe that Medicare beneficiaries, or indeed any person, should need to become insurance specialists merely to preserve access to familiar doctors, medications, and treatments. A plan can change its premiums, drug tiers, network, and benefits from one year to the next. Authorization and reimbursement decisions can arrive without warning, leaving the hapless beneficiary to untangle every difference. This can be crazy-making!
What’s an old guy to do? Aging brings enough challenges of its own. Wrestling with Medicare should not be one of them.
Soundtrack Suggestion